An annual operating plan (AOP) is the document that turns an ecommerce brand's goals for the year into numbers: revenue targets by channel, the ad budget behind them, the inventory buys that stock them, and the hires that run them. It is approved once and monitored monthly, so the CEO, the COO and anyone lending to or investing in the brand can see each month whether the year is on plan.
This page is the template. The full structure is published below, section by section, with worked numbers for an illustrative brand selling on Shopify, Amazon and wholesale. Copy the tables into a sheet and replace the figures with your own. The plan draws on the same numbers as your monthly P&L, so our ecommerce P&L template is a useful companion if you are setting up the categories for the first time.
Why most AOP advice does not fit a brand
Search for annual operating plan guidance and you will find enterprise planning cycles: top-down targets, department budgets, reconciliation meetings and a long executive summary. That process exists because a large company has dozens of budget owners who need to negotiate with each other.
A brand under $10 million in revenue has a handful of decision makers and one constraint that dominates the rest, which is cash tied up in stock. The factory wants a deposit months before the goods sell, the marketplaces pay out on their own schedule, and wholesale buyers pay on terms. A plan that sets revenue targets without placing the purchase orders in the months they get paid is a wish list.
A brand's AOP should therefore be one connected model. Channel targets set the inventory you need, the inventory sets the purchase orders and their payment dates, the ad budget sets how fast the stock sells, and all four set the cash. It fits on a few pages, the owners agree to it in December or January, and the only ongoing meeting is a monthly comparison of plan against actuals.
What an ecommerce annual operating plan contains
Five sections cover what an owner needs to agree to and what a team needs to run. First, revenue targets by channel and by quarter. Second, the ad budget by channel. Third, the inventory buys, with deposit and balance dates. Fourth, the hiring plan and the rest of the operating budget. Fifth, the review cadence that keeps the plan in use after January.
The annual operating plan template
The worked example is a brand that sold $4.8 million last year and plans $6.0 million this year: 45% on Shopify, 40% on Amazon and 15% to wholesale accounts. Every number is illustrative, a figure to react to rather than a benchmark to hit.
Revenue targets by channel
Start with the channel split, because each channel carries a different cost to sell and a different payout timing.
| Channel | Net revenue target | Share of revenue | Ad budget | Ad budget as share of channel revenue |
|---|---|---|---|---|
| Shopify | $2,700,000 | 45% | $540,000 | 20% |
| Amazon | $2,400,000 | 40% | $300,000 | 12.5% |
| Wholesale | $900,000 | 15% | $60,000 | 6.7% |
| Total | $6,000,000 | 100% | $900,000 | 15% |
The wholesale line looks cheap on ads because its cost sits elsewhere: trade terms, samples, and the cash that waits 60 or 90 days for the buyer to pay. Read each channel through its contribution margin, what is left after landed cost, fees, fulfillment and ads, rather than through revenue alone.
Targets by quarter
Seasonality is the reason a brand plans by quarter. Many consumer brands sell more in the fourth quarter than in any other, and the stock for it is paid for in the third.
| Quarter | Net revenue | Ad spend | Contribution margin (31%) |
|---|---|---|---|
| Q1 | $1,200,000 | $180,000 | $372,000 |
| Q2 | $1,300,000 | $195,000 | $403,000 |
| Q3 | $1,400,000 | $210,000 | $434,000 |
| Q4 | $2,100,000 | $315,000 | $651,000 |
| Year | $6,000,000 | $900,000 | $1,860,000 |
The ad budget holds at 15% of revenue in every quarter here. In practice many brands spend ahead of the season and let the share fall in December, and the plan should say which approach the owners chose, so a heavy October does not read as overspending when it was the plan.
Inventory buys
This is the section most plans leave out, and the one that decides whether the year is survivable. List every purchase order with its deposit and its balance in the month each is paid.
| Order | Placed | Deposit (30%) | Balance paid | Factory total |
|---|---|---|---|---|
| Spring range | January | $144,000 | March | $480,000 |
| Summer range | April | $156,000 | June | $520,000 |
| Holiday range | July | $228,000 | September | $760,000 |
| Holiday reorder | September | $132,000 | October | $440,000 |
| Year | $660,000 | $2,200,000 |
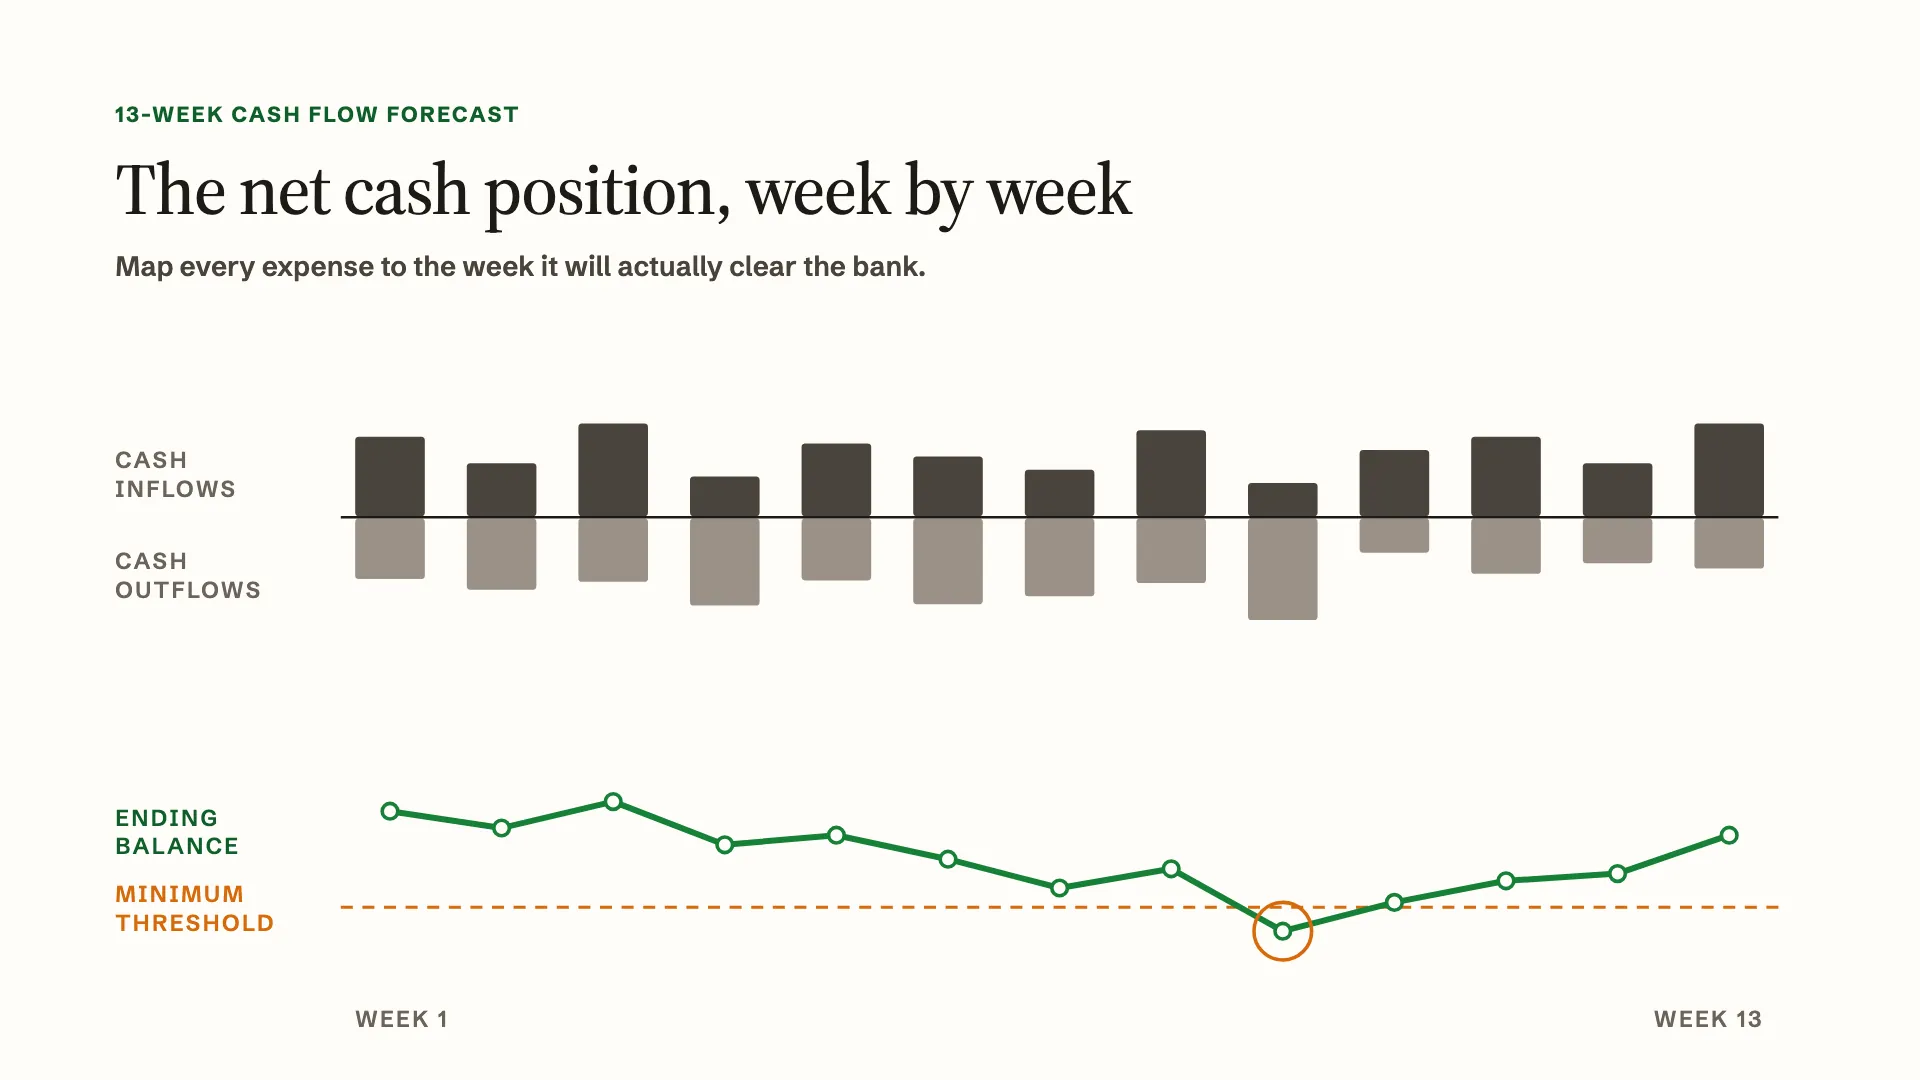
September is the month to watch. It carries $664,000 of factory payments, the $532,000 holiday balance and the $132,000 reorder deposit, before the fourth quarter's sales have paid out. If the plan shows cash dipping below the brand's minimum that month, the honest fixes are a smaller reorder, a later deposit agreed with the factory, or an inventory line arranged before summer. Our guide to inventory and PO financing covers the options, and a 13-week cash flow forecast is the tool for watching that month as it approaches.
Hiring plan and operating budget
Headcount is usually the largest cost outside the contribution line. List each planned hire with a start month, a monthly cost including taxes and benefits, and the condition that releases the offer.
| Role | Start month | Monthly cost | Hiring trigger |
|---|---|---|---|
| Customer service lead | February | $5,500 | Tickets above 400 per week for a month |
| Marketplace manager | April | $7,500 | Amazon revenue above $500,000 for the first quarter |
| Wholesale account manager | July | $7,000 | 25 active wholesale accounts |
| Seasonal support (two people) | October to December | $9,000 | Holiday range delivered on time |
The trigger column is what makes the plan useful when a quarter lands light. If Amazon misses its first-quarter number, the marketplace hire waits without a fresh argument, because the owners agreed in advance that revenue, not the calendar, releases the offer.
The operating budget then sits under the contribution margin and shows what the year is expected to earn.
| Line | Annual budget | Share of revenue |
|---|---|---|
| Contribution margin | $1,860,000 | 31% |
| Payroll, including the hires above | $960,000 | 16% |
| Agencies and creative | $180,000 | 3% |
| Rent and other overheads | $120,000 | 2% |
| Software and tools | $90,000 | 1.5% |
| Accounting, legal and insurance | $90,000 | 1.5% |
| Contingency | $120,000 | 2% |
| Operating profit | $300,000 | 5% |
About $197,000 of the payroll line is the four new roles at their planned start months. Keep the contingency line even under pressure to trim it; the surprises it absorbs, a freight spike or a delayed container, otherwise come straight out of cash.
Review cadence
The last section says how the plan gets checked. Writing the cadence into the plan means the owners commit to the loop before the year gets busy.
| Cadence | What is reviewed | Decision on the table |
|---|---|---|
| Annually (December to January) | The full plan, all five sections | Agree the targets and the spend and inventory they authorize |
| Quarterly | Actuals and a reforecast against the original plan | Confirm or change the next quarter's buys, release or hold hires |
| Monthly | One page of budget against actuals by channel | Explain the gaps that matter and agree what changes |
The monthly page is the one most brands skip, and it is what keeps the plan in use after January. Our guide to budget vs actuals covers how to build it and which gaps deserve attention, and variance analysis explains the method.
Build it as one connected model
The five sections above are views of one model, not five documents. Channel targets set the stock, the stock sets the purchase orders, the purchase orders set the cash, and the ad budget sets how fast the stock turns into revenue. Change an assumption, such as a slower Amazon quarter or a factory price increase, and the effect should flow through to the cash month by month. If the targets live in a slide and the inventory buys live in a separate sheet, the two will disagree by March.
Resist the urge to model precision you do not have. The value of the plan lies in assumptions that are written down and can be checked. A useful addition is a downside case agreed in advance: if Q2 revenue lands 15% under plan, the summer range is cut by a set amount and the next hire waits. A hard quarter then triggers a decision the owners already made instead of a scramble.
Keep the plan alive after January
The plan earns its keep in months two through twelve. Each month, compare actuals to plan by channel, by ad budget and by inventory, explain the gaps that matter, and record what changes. Most months this takes under an hour. When a month goes badly, it is the reason the brand notices in time.
Change the plan when the business changes materially, not every time a month wobbles. A new channel, a lost wholesale account, or two quarters well off target justify a formal revision. Rewriting the plan after every variance destroys the baseline, and defending stale numbers all year destroys trust in it.
The reason this loop fades at most brands is timing. When the books are finished three weeks after month end, the monthly review becomes an argument about numbers nobody trusts yet, and the meeting drops off the calendar by summer.
That is the part Futureproof covers. Your budget sits beside the books category by category, the actuals come from the same books your bookkeeper or fractional CFO finishes each month, and the cash forecast places each factory deposit and balance in its week against your minimum cash. Ecommerce pricing starts at $1,000 per month. Book a demo for a walkthrough of the whole platform.
Frequently asked questions
What is an annual operating plan for an ecommerce brand?
An annual operating plan is a brand's agreed plan for one year: revenue targets by channel and quarter, the ad budget by channel, the inventory buys with their payment dates, the hiring plan and the operating budget. It turns the year's goals into numbers that can be checked against actual results every month.
What is the difference between an annual operating plan and a budget?
The budget is one part of the annual operating plan, the spending side. The plan wraps the budget in the targets and inventory buys that the spending supports, so the owners agree to the whole trade at once: this ad budget and these purchase orders, for these channel targets, with cash staying above its minimum.
When should an ecommerce brand build its first annual operating plan?
A brand should build its first annual operating plan once it sells on more than one channel or places purchase orders months ahead of the season. At that point the cash tied up in stock is large enough that the year needs to be planned month by month. Taking on an inventory lender or an investor usually makes it necessary.
How should inventory buys appear in an annual operating plan?
Each purchase order should appear in the month its deposit is paid and again in the month its balance is paid, not only when the goods arrive. That shows the month cash is lowest, usually late summer for a brand with a strong fourth quarter, and lets the owners decide in advance whether to cut an order, move a deposit or arrange financing.
How often should an annual operating plan be updated?
Review it monthly, reforecast it quarterly and change it rarely. The monthly review compares actuals to plan and explains the gaps. The quarterly reforecast updates the outlook and the next quarter's inventory buys while keeping the original plan as the baseline. Formal changes are for material events such as a new channel or two quarters well off target.