Budget vs actuals is the practice of comparing what a brand planned to sell and spend against what happened, line by line. The gap between the two numbers is called a variance, and the process of explaining those gaps is variance analysis. For an ecommerce brand it is the fastest way to find out whether the plan for ad spend, inventory, landed cost and channel fees is holding.
Most brands under $10M never write a full budget. They plan the next inventory order and a monthly ad number, then find out at month end whether either held. Meanwhile ad spend drifts toward whichever channel looked good last week. A monthly budget vs actual report closes that loop. It tells you where reality moved away from the plan, by how much, and whether the gap is a problem or a signal to change the plan itself.
This guide covers how to build a budget vs actual report, how to calculate variances, what variance thresholds deserve attention as a brand grows, and how to run the analysis without losing a week of your month to spreadsheet assembly. It is part of our complete guide to ecommerce accounting.
What does a budget vs actual report show?
A budget vs actual report places three or four columns side by side for every line on your income statement: the budgeted amount, the actual amount, the dollar variance, and the percentage variance. Most brands run it monthly for the month just ended and for the year to date.
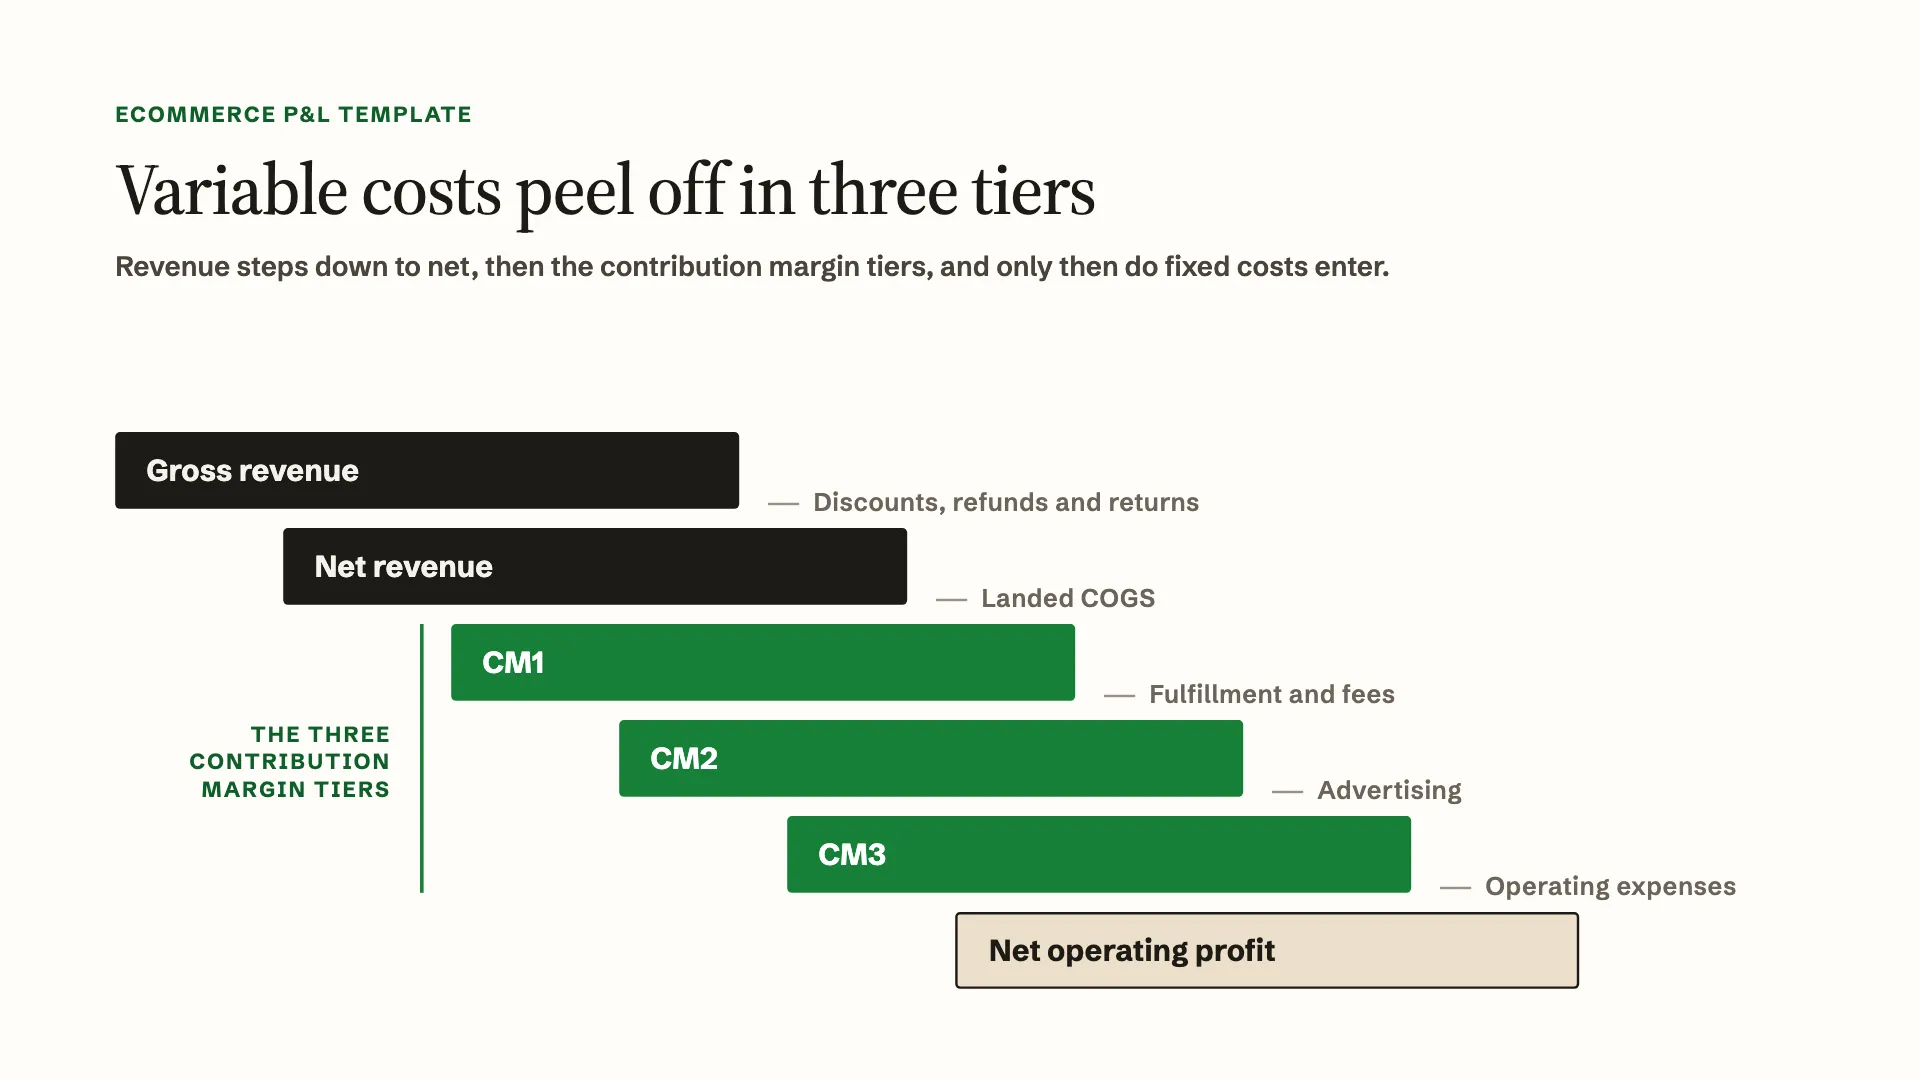
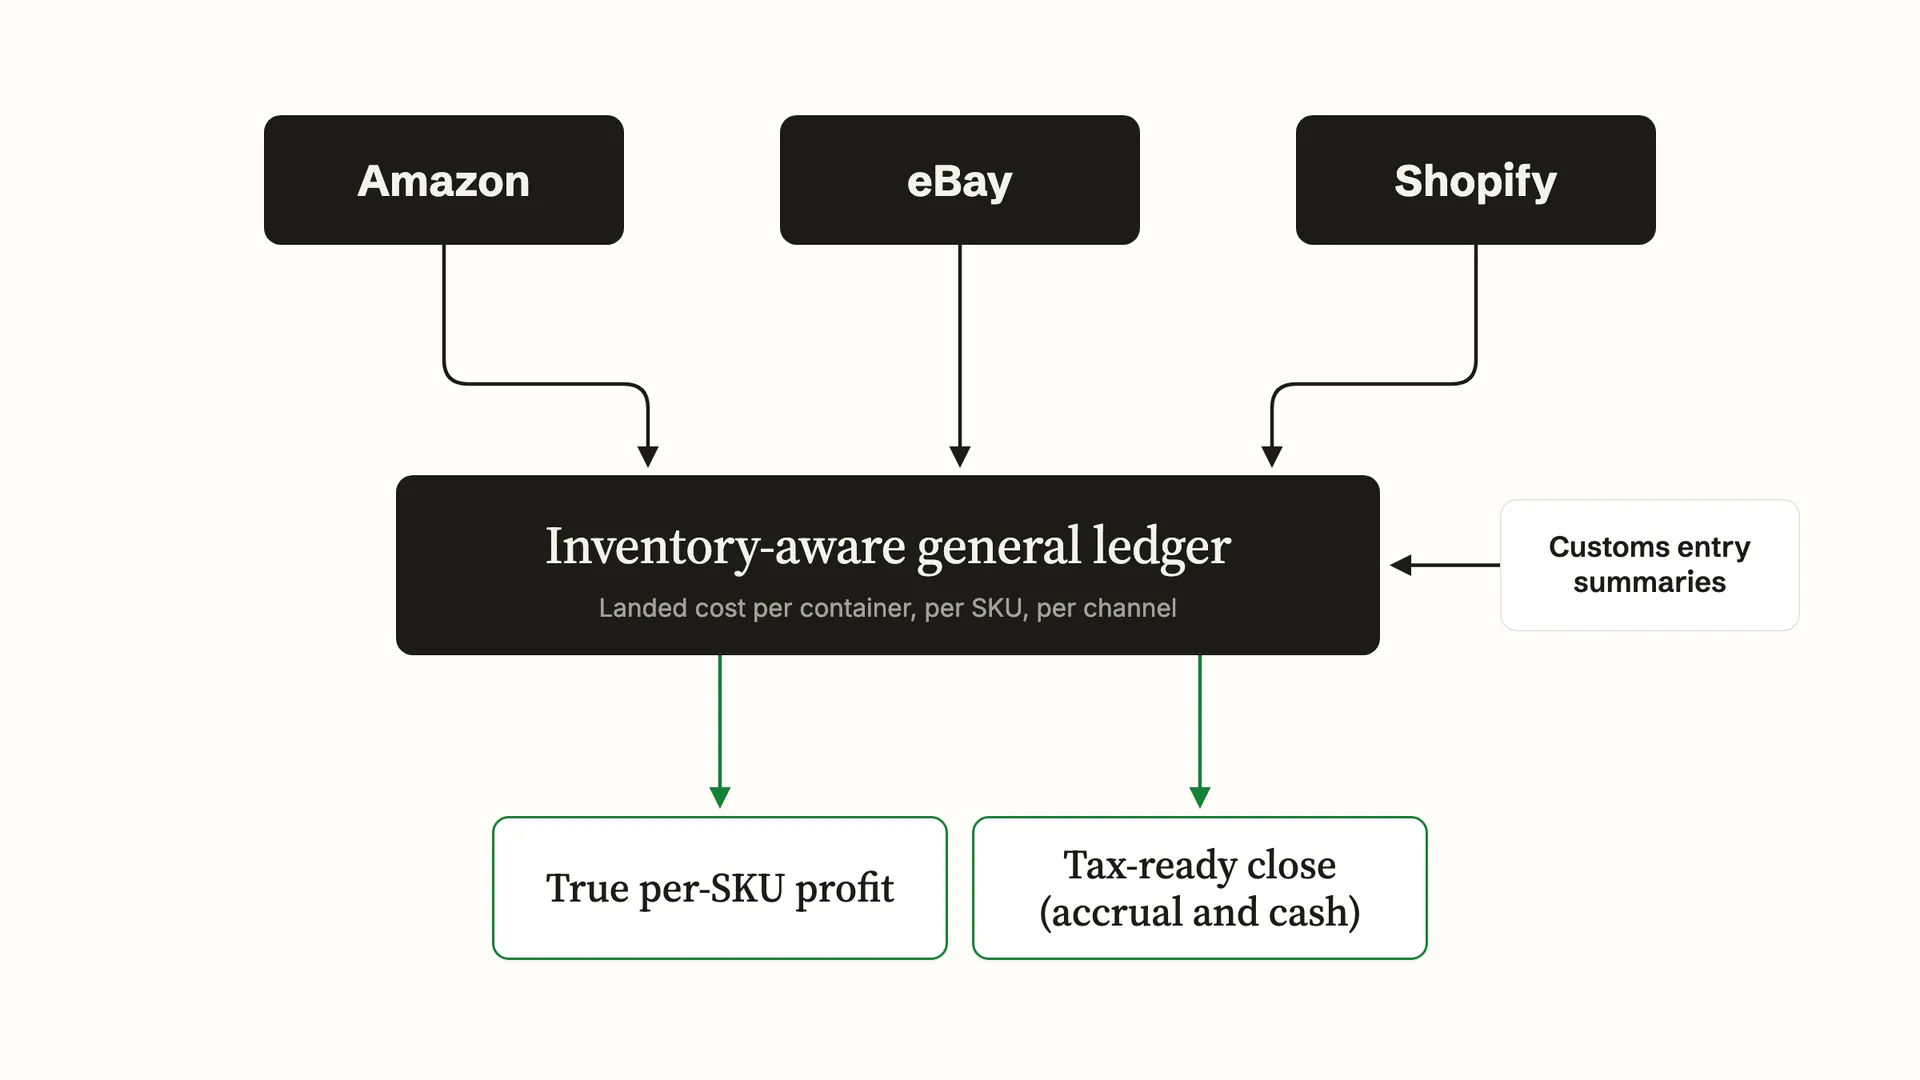
For a brand, the lines that move most are the ones a generic template lumps together. Revenue should be split by channel, since Shopify, Amazon and eBay each carry their own fees and returns. Cost of goods sold should carry landed cost, meaning the supplier price plus freight, duty and the other costs of getting a unit to the warehouse. Channel fees, fulfillment and ad spend by channel each deserve their own line, because each is a decision someone made and can change.
The report only means something if the actuals are trustworthy. That is why budget variance analysis belongs inside a disciplined month-end close rather than floating alongside it. If a payout was booked as one net deposit or a supplier bill has not been recorded, the variance columns describe your bookkeeping lag, not your business. Close the books first, then compare. And compare on the same basis: measuring cash paid to a supplier against a cost of goods budget manufactures variances that are timing artifacts, not business signals.
Variances come in two flavors. A favorable variance means the result was better than planned: higher revenue, lower cost. An unfavorable variance means the opposite. The labels describe direction, not importance. A favorable variance can still be a warning, such as underspending on Amazon Ads because a listing was suppressed and the campaigns paused.
The discipline matters beyond internal decisions. Lenders ask for a P&L and a forecast before an inventory line, and a forecast is only as credible as your record against the last one. Acquirers ask for budget vs actual comparisons in diligence. An owner who can explain every material variance in plain language reads differently from one who discovers the gaps live on the call.
How do you calculate budget variance?
The math is deliberately simple. For expense lines:
Dollar variance = Actual minus Budget. Percentage variance = (Actual minus Budget) divided by Budget.
An expense line that budgeted $10,000 and spent $12,000 has a $2,000 unfavorable variance, or 20 percent over plan. For revenue lines the interpretation flips: actuals above budget are favorable.
Two conventions keep reports readable. First, pick a sign convention and hold it everywhere, since flipping signs between revenue and expense sections is the most common source of confusion in owner-built spreadsheets. Second, show both the dollar and the percentage. A 40 percent variance on a $500 software line is trivia. A 4 percent variance on a $400,000 inventory line is real money.
The percentages only tell you what happened. The analysis is the sentence you write next to each material variance explaining why it happened and what you will do about it. "Meta ran 20 percent over budget because the spring launch creative was scaled a week early; moving $4,000 from June Meta to Amazon Ads" is variance analysis. The number alone is not.
What does a worked example look like for a brand?
The illustration below shows a simplified monthly budget vs actual report for a hypothetical brand selling on Shopify and Amazon, budgeted at $250,000 in monthly net revenue. The numbers are constructed for teaching, not drawn from benchmark data.
| Line item | Budget | Actual | $ Variance | % Variance | Direction |
|---|---|---|---|---|---|
| Net revenue, all channels | $250,000 | $238,000 | -$12,000 | -4.8% | Unfavorable |
| Cost of goods sold, at landed cost | $100,000 | $99,960 | -$40 | 0.0% | Looks on plan |
| Channel and payment fees | $30,000 | $31,900 | +$1,900 | +6.3% | Unfavorable |
| Ad spend, Meta | $22,000 | $26,400 | +$4,400 | +20.0% | Unfavorable |
| Ad spend, Amazon Ads | $12,000 | $9,000 | -$3,000 | -25.0% | Favorable |
| Fulfillment and shipping | $20,000 | $19,500 | -$500 | -2.5% | Favorable, immaterial |
| Team, software and other overhead | $45,000 | $45,900 | +$900 | +2.0% | Unfavorable, immaterial |
| Operating profit | $21,000 | $5,340 | -$15,660 | -74.6% | Unfavorable |
Read as a whole, the report tells a story no single line reveals. Cost of goods sold matched the budget almost to the dollar, which looks fine until you notice that it did so on $12,000 less revenue. Cost of goods ran 42 percent of revenue against a planned 40 percent, so cost of goods rose as a share of revenue: a freight increase, a supplier price change, deeper discounts or a shift toward lower-margin products. Channel fees ran over on lower sales for the same kind of reason: the fee rate climbed from 12 percent of revenue to about 13.4 percent, which points to a channel mix moving toward the marketplace. Meanwhile Meta ran 20 percent hot while Amazon Ads ran 25 percent under, and revenue missed by 4.8 percent.
None of those lines is alarming alone. Together they cut operating profit from $21,000 to $5,340, about three quarters of the planned profit gone, without anyone making a single decision to spend more.
That is the reason this report exists. Small monthly variances compound. If landed cost stays two points above plan for a year at budgeted sales of $250,000 a month, the brand gives up $60,000 of gross profit. Our guide to true landed cost per SKU shows where those two points usually come from.
Where do inventory buys fit in the budget?
Inventory purchases do not appear on the income statement when you pay for them. The stock on a $150,000 purchase order sits on the balance sheet as inventory and reaches cost of goods sold only as the units sell. So a brand needs two budgets that talk to each other: the profit budget above, and a purchasing budget that says how much stock it plans to buy and when the deposit and balance fall due.
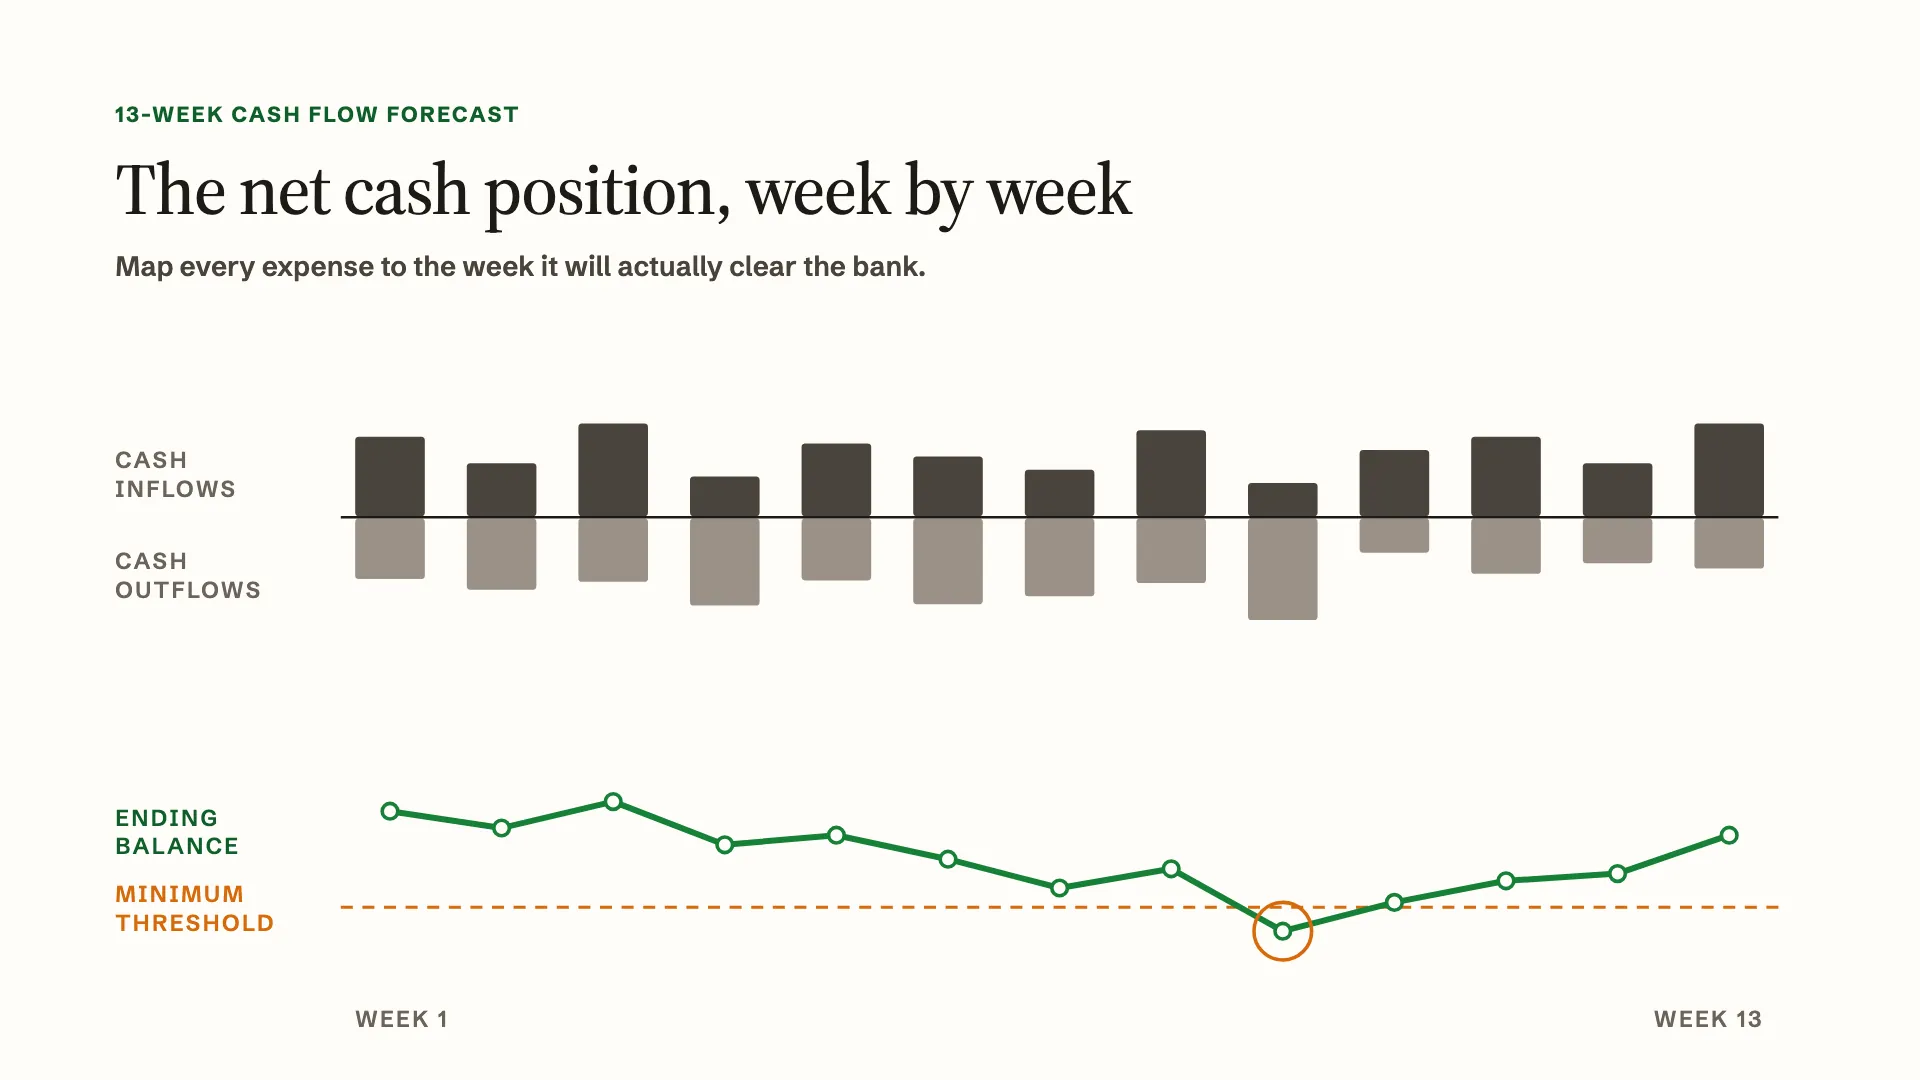
Compare the purchasing budget against the purchase orders placed and the supplier bills received each month. A brand that buys 30 percent more inventory than planned can hit its profit budget exactly and still run short of cash, because the money left the bank long before the units sell. That is why the purchasing budget belongs next to a 13-week cash flow forecast rather than in a separate file.
If you have not built the budget side yet, start with a channel P&L. Our ecommerce P&L template gives the structure, and contribution margin by channel is the line most budgets should be built around.
Which variance thresholds matter as a brand grows?
Corporate FP&A teams investigate every variance above a fixed size they set in advance, the point where a gap is big enough to matter. Smaller brands need a different posture, because an early budget is a guess by design and the cost of investigating everything exceeds the value. A practical rule set, based on how we see brands operate at each size:
| Annual revenue | Investigate expense variances above | Revenue variance posture | Cadence |
|---|---|---|---|
| Under $1M | 20% and $2,000+ on a line | Plan is a hypothesis; track direction, not precision | Monthly, lightweight |
| $1M to $5M | 10-15% and $5,000+ on a line | Explain any miss over 10%, by channel | Monthly, full P&L |
| Over $5M | 5-10% or any line a lender or partner sees | Explain every material miss in the monthly pack | Monthly, with quarterly reforecast |
Treat these as starting points to adjust, not audited benchmarks. The pattern behind them is what matters: as the brand grows, the threshold for "worth explaining" drops, and the consequences of a miss shift from internal course correction to credibility with lenders, partners and eventually buyers.
The dual threshold, a percentage and a dollar floor, keeps the exercise honest at every size. Percentage alone drags you into investigating $80 variances on small lines. Dollars alone lets a 50 percent overrun on a growing ad channel hide until it is large.
One more habit separates clean operators from chaotic ones: when a variance reflects a permanent change rather than a one-time event, update the forecast. A supplier price increase is permanent. A one-off freight surcharge is not. Budget vs actuals tells you the plan diverged from reality. A reforecast decides which one moves.
Why is the report usually late?
The standard failure mode is timing. The books close on day ten (the slowest quartile of companies in APQC's close-cycle benchmark take 10 or more calendar days), someone exports the P&L, pastes it into a spreadsheet next to the budget, fixes the rows that no longer line up because the chart of accounts changed, and circulates the report around day fifteen, right where APQC's data on period-end management reporting puts the bottom quartile. By then the next month's ad budget is half spent, and the findings are history rather than decisions.
The spreadsheet step is also where quiet errors creep in. For a brand the usual one is the payout: a settlement booked as a single net deposit hides the fees inside revenue, so the fee line looks under budget and revenue looks low. A budget vs actual report built on unreconciled actuals is worse than no report, because it manufactures false confidence.
The fix is structural. Variance reporting has to be a byproduct of the close, not a project that starts after it. When payouts are reconciled as they land and the budget lives next to the general ledger instead of in a separate file, the report is ready the moment the books are, and the meeting about it can happen in the first week of the month instead of the third.
That is how Futureproof works. Your budget sits beside the books category by category, the actuals come from the same ledger your bookkeeper or fractional CFO closes each month, and you can open the transactions behind any gap and leave a note on it. Ecommerce pricing starts at $1,000 per month. Book a demo for a walkthrough of the whole platform.
Frequently asked questions
How often should a brand run a budget vs actual report?
Monthly is the standard, timed to the close of the books, with a year-to-date view alongside the single month. Brands with reconciled books often check ad spend and channel fees weekly during peak season and keep the monthly report for formal review. Quarterly-only reporting is too slow, because a bad quarter is three months of unexamined drift in ad spend and landed cost.
What percentage variance is significant?
There is no universal number, which is why fixed answers like "10 percent" mislead. Significance depends on brand size, line size, and repetition. A useful default is to investigate expense lines that miss by more than 10 to 15 percent and more than a few thousand dollars, tightening toward 5 to 10 percent past $5 million in revenue. Any variance that recurs for three consecutive months is significant regardless of size, because it means the budget is wrong or the spending is unmanaged.
What is the difference between budget vs actuals and a forecast?
The budget is the fixed plan approved at the start of the period, and actuals are the recorded results. Budget vs actuals compares those two. A forecast is the living estimate of where the period will land, updated as new information arrives. Well-run brands track all three: actuals against budget for accountability, and forecast against budget to see problems before they become actuals.
What causes budget variances for an ecommerce brand?
Four causes cover most cases. Timing is when a cost landed in a different month than planned, such as a supplier bill or an annual software renewal. Price is when the amount per unit changed, such as freight or a fee rate. Volume is when activity changed, such as orders running above plan. Plan error is when the budget assumption was wrong. Labeling each material variance with one of these causes turns the report from a scorecard into a diagnostic.
Do small brands need budget vs actual reports?
Yes, and the report is simpler at small scale because there are fewer lines. A brand under $1 million in sales lives on its ad spend and its next inventory order, so a monthly comparison of planned against actual spend on those two lines is the most direct check on the plan. It also builds the reporting habit before a lender or partner starts asking for it.